HASiL Clarifies Stamp Duty on Employment Contracts: RM3,000 Salary Threshold and Supplementary Documents
Updated: 7 August 2026
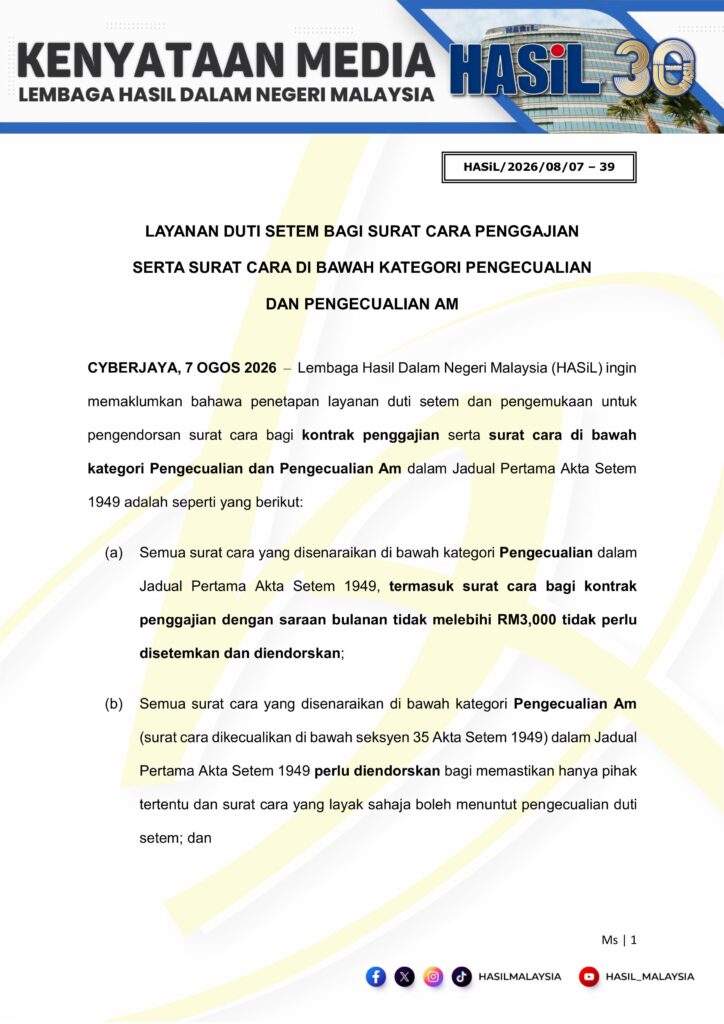
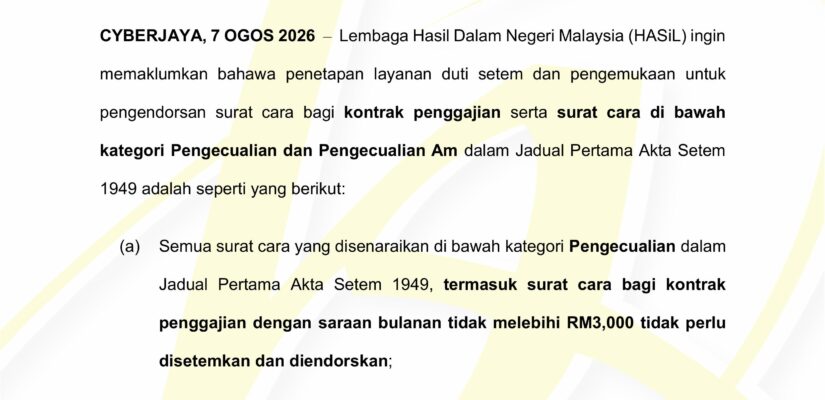
The Inland Revenue Board of Malaysia (HASiL) has issued an important clarification on the stamp duty treatment of employment-related instruments.
The latest announcement provides greater clarity for employers, particularly on employment contracts for employees earning RM3,000 or below per month and the treatment of supplementary employment documents.
What Employers Need to Know
The key points from HASiL’s clarification are:
1. Employment Contracts for Employees Earning RM3,000 or Below
Where an employee’s monthly remuneration does not exceed RM3,000, the employment contract is exempt from stamp duty.
Importantly, HASiL clarified that these employment contracts do not need to be submitted for stamping or endorsement.
In simple terms:
Monthly remuneration RM3,000 or below → No stamping or endorsement required.
This should significantly reduce the administrative burden for employers with a large number of employees within this remuneration range.
2. Employment Contracts Above RM3,000
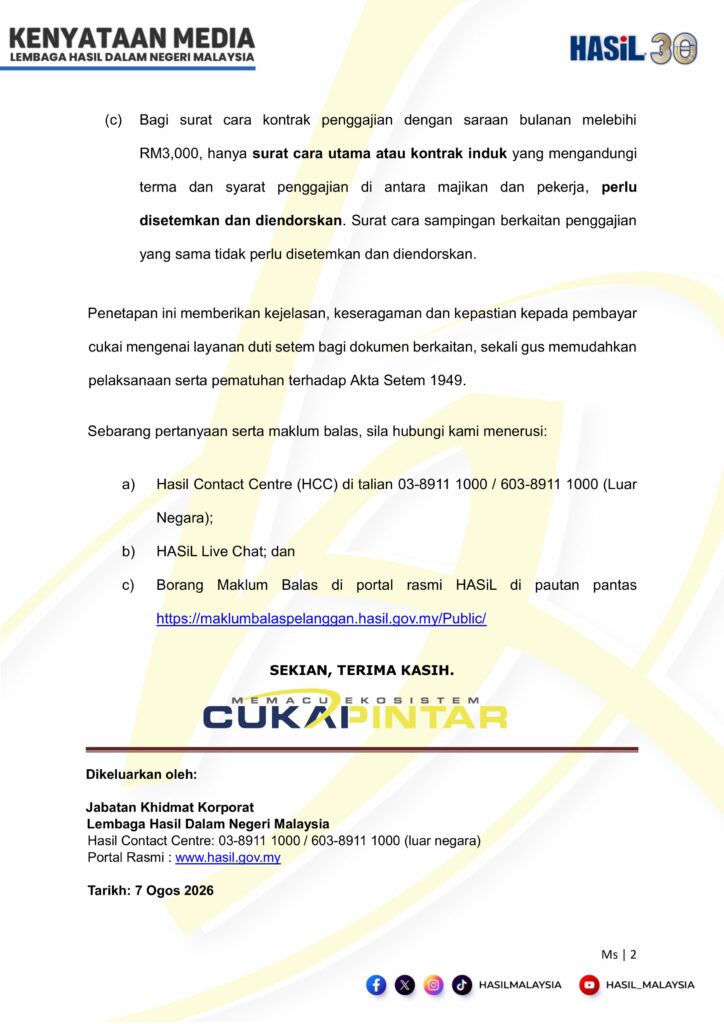
Where an employee’s monthly remuneration exceeds RM3,000, the main employment contract containing the terms and conditions agreed between the employer and employee is subject to the applicable stamp duty treatment.
The main employment contract should therefore be submitted for stamping and endorsement.
Monthly remuneration above RM3,000 → Main employment contract must be stamped.
Employers should ensure that employment contracts falling within this category are handled in accordance with the Stamp Act 1949 and the applicable stamping requirements.
3. What About Supplementary Employment Documents?
Another important clarification concerns documents issued after the main employment contract.
According to HASiL, supplementary instruments relating to the same employment do not need to be separately stamped or endorsed.
This is particularly relevant because employers may issue various documents throughout an employee’s service.
Where the document is supplementary to the same employment relationship, separate stamping or endorsement is not required based on HASiL’s latest clarification.
Quick Reference for Employers
| Employment Document | Requirement |
|---|---|
| Employment contract – monthly remuneration RM3,000 or below | No stamping or endorsement required |
| Employment contract – monthly remuneration above RM3,000 | Main employment contract to be stamped and endorsed |
| Supplementary document relating to the same employment | No separate stamping or endorsement required |
What Should Employers Do Now?
Employers and HR teams should review their current employment contract stamping procedures in light of this clarification.
In particular, employers should:
- Identify employees whose monthly remuneration exceeds RM3,000 and ensure the relevant main employment contracts are properly stamped.
- Avoid unnecessary submission of employment contracts for employees earning RM3,000 or below where the exemption applies.
- Review whether documents issued after the main employment contract are supplementary documents relating to the same employment before submitting them separately for stamping.
- Maintain proper employment documentation and records to support the employment relationship and applicable stamp duty treatment.
Why This Clarification Matters
Employment contract stamping has become an important compliance issue for Malaysian employers.
The latest clarification provides a much clearer distinction between employment contracts that require stamping and those that are exempt.
For many employers, the most important takeaway is:
RM3,000 or below per month: no stamping or endorsement required. Above RM3,000 per month: stamp the main employment contract.
The clarification regarding supplementary documents should also help reduce unnecessary administrative work where multiple documents are issued during the same employment relationship.
Frequently Asked Questions
Does an employment contract need to be stamped if the employee earns RM3,000 per month?
No. Based on HASiL’s clarification dated 7 August 2026, an employment contract where the employee’s monthly remuneration does not exceed RM3,000 is exempt and does not require stamping or endorsement.
What if the employee earns RM3,001 per month?
Where the monthly remuneration exceeds RM3,000, the main employment contract should be submitted for stamping and endorsement.
Do supplementary employment documents need to be stamped?
HASiL clarified that supplementary instruments relating to the same employment do not need to be separately stamped or endorsed.
Does this mean every HR letter issued after the employment contract is automatically exempt?
Not necessarily. Employers should consider whether the document is genuinely supplementary to the same employment relationship. Documents creating a new or separate contractual arrangement may need to be considered differently.
Conclusion
HASiL’s 7 August 2026 clarification provides welcome guidance for employers managing employment contract stamping.
The key rule for HR teams to remember is straightforward:
RM3,000 and below → No stamping required
Above RM3,000 → Stamp the main employment contract
Employers should update their internal HR processes accordingly and ensure that contracts requiring stamping continue to be handled within the applicable requirements.
Source: Inland Revenue Board of Malaysia (HASiL), Layanan Duti Setem Bagi Surat Cara Penggajian Serta Surat Cara Di Bawah Kategori Pengecualian Dan Pengecualian Am, 7 August 2026.